As the fourth quarter begins, the split in Hong Kong's office market is not simply "core versus outlying districts" — it runs by building grade.
Demand for Central's Grade A space is supported by IPO preparation, financial-sector activity and family offices setting up headquarters. We expect Central Grade A rents to rise a further 5% or more in Q4. Outside Central Grade A — including Central's own Grade B stock, offices in other districts, industrial space and shops — leasing take-up remains weak after three quarters of rental decline this year.
The site figures below are calculated from live listings on our own platform, as at 30 September 2026 (the handover point between Q3 and Q4).
Central Is Not One Market: Four Price Tiers in the Same District
Central has 431 live office listings. Split by the grade of the building each listing sits in, the spread within Central alone is wider than many expect:
| Grade | Live listings | Average rent (HK$/sq ft) |
|---|---|---|
| AAA | 48 | 127.1 |
| AA | 68 | 90.2 |
| A | 70 | 55.6 |
| B+ | 5 | 58.3 |
| B | 187 | 44.3 |
| Unrated | 48 | approx. 48 |
The median rent for Central Grade A space (AAA/AA/A) is HK$80 per sq ft, against HK$52 for Central as a whole. The gap comes from Grade B stock: Central has 187 live Grade B listings — the largest group in the district — averaging HK$44.3 per sq ft.
In other words, the commonly quoted "HK$52 for Central" blends Grade A and Grade B together. The tiers actually driven by IPO and family-office demand are the top two (AAA and AA), while the 187 Grade B listings in Central face conditions closer to Grade B space in outlying districts. Our two calls for Q4 — Grade A rising, Grade B soft — therefore hold *within* Central as well as across districts.
(AAA/AA/A here are our own sub-tiers within the official "Grade A" band, not a government classification. The official system has only Grades A, B and C.)
Central Grade A: Demand From Three Client Types
Three types of occupier are currently driving demand for Central Grade A space:
- Companies preparing to list in Hong Kong — the preparation phase requires a core-district office
- Family offices — both new set-ups and expansions, favouring core-district Grade A space
- Financial and professional services firms — expansion by existing tenants
What they share is a specific requirement on location and building specification, which leaves few substitutable options and narrows the room to negotiate compared with other districts. Provided IPO and financial activity hold up, we expect Central Grade A rents to rise a further 5% or more in Q4.
Live levels in the other core districts: Admiralty HK$52 (49 listings), Causeway Bay HK$45 (135), Mong Kok HK$38 (72), Tsim Sha Tsui HK$35 (247), Wan Chai HK$33.8 (285), Sheung Wan HK$32.1 (186).
Our Own Deal: Pre-IPO Requirement at Over HK$90 per sq ft
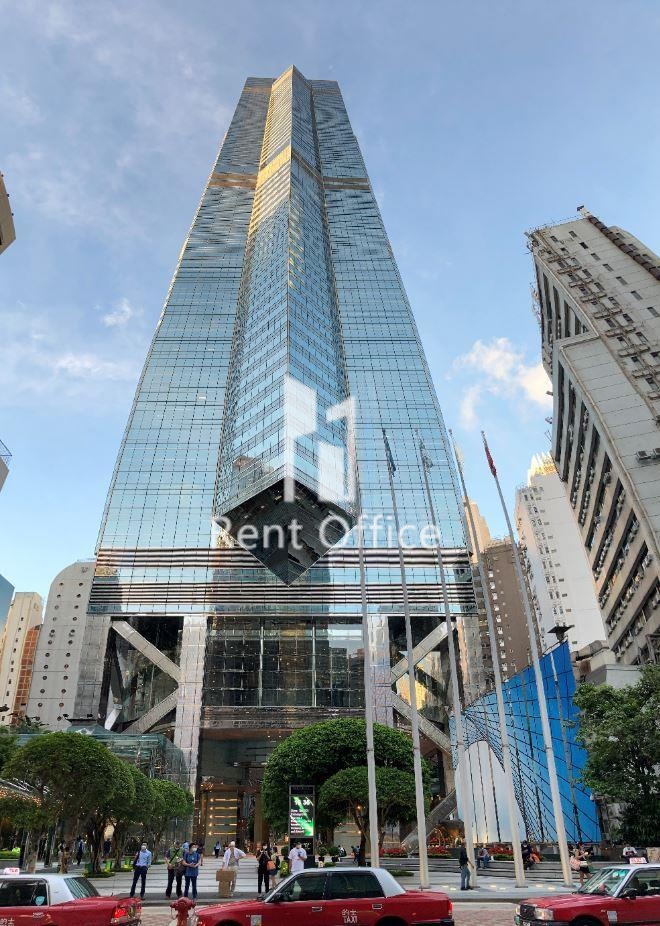
Candice Choi and her team recently completed a leasing transaction for a mainland aviation-finance client entering Hong Kong. The client took Grade A office space at 3 Garden Road for Pre-IPO preparation, at a rent of over HK$90 per sq ft.
Placed against the tiered data above, the deal sits clearly: over HK$90 corresponds to the AA tier in Central (which averages HK$90.2 in live listings) — above the HK$80 median for Central Grade A overall, and well above the HK$52 blended district median.
Two points follow. First, occupiers with an IPO-preparation requirement transact at the upper tiers of core-district Grade A, not at the district average. Second, any reference to "Central rents" needs to state which tier is meant — reading a HK$90 Grade A deal through a HK$52 figure, or using HK$90 to infer a general level for Central, both mislead.
Leasing of this type tends to move on a short decision cycle, carries specific requirements on building specification and address, and is often willing to pay a premium for location — precisely the demand now supporting Central Grade A asking rents.
Outside Central Grade A: Take-Up Still Weak After Three Quarters of Decline
After three quarters of rental decline this year, leasing take-up for offices in other districts, Grade B space, industrial space and shops remains weak — lower asking rents have not translated into a corresponding recovery in transaction volume.
Kowloon East/West and the New Territories offices: Cheung Sha Wan HK$22.4 (124 listings), Kwun Tong HK$20 (194), Kowloon Bay HK$20 (56), Lai Chi Kok HK$19.5, Tsuen Wan HK$19, Kwai Chung HK$18.8. Kwun Tong ranks fourth city-wide by live listing count at 194 — supply is not concentrated in the highest-rent districts.
Industrial: 613 live listings. Median rents are highest in Cheung Sha Wan at HK$18.6, Lai Chi Kok HK$18 and Shek Mun HK$16; Kwun Tong HK$15.5, Kowloon Bay HK$15.4, Tsuen Wan HK$13, with Kwai Chung and Tuen Mun lowest at HK$12. Supply is largest in Kwai Chung (109), Tsuen Wan (102) and Kwun Tong (78).
The office-to-industrial gap within the same district varies sharply: in Lai Chi Kok the two differ by only HK$1.5 (HK$19.5 against HK$18), so substituting industrial space saves little; in Wong Chuk Hang the gap is HK$10.7 (HK$24.6 against HK$13.9). The size of that gap determines how much the "switch to industrial space" option is actually worth in each district.
Shops: 191 live listings, but several districts have samples of only 2 to 7, too few for a median to represent the district. No shop figures are given in this article.
Site-Selection Notes for Q4
If you need a core-district address, secure it early — but be specific about which tier. Room to negotiate on Central Grade A has narrowed; where the business itself requires a core-district address (IPO preparation, financial-facing work), continuing to wait may cost more than committing now. That said, AAA and Grade B in the same Central differ by nearly three times on average — "moving into Central" can mean two very different budgets.
Central Grade B and outlying districts still offer room to negotiate. Weak take-up works in tenants' favour: where new supply remains unabsorbed, landlords are generally more willing to move on rent-free periods and rental terms. Central's 187 live Grade B listings fall into this category too.
Compare total occupancy cost, not just rent per sq ft. Management fees, rates, government rent, fit-out and reinstatement all need to be counted. Central at HK$52 against Tsuen Wan at HK$19 is a gap of roughly 2.7 times on rent alone; once total occupancy cost is included, the real gap may differ and has to be worked out case by case.
Check the same-district gap before treating industrial space as a substitute. As shown above, the office-to-industrial gap ranges from HK$1.5 to HK$10.7. Where the gap is narrow, the rent saved may not offset the compromise on specification.
Serviced offices belong in a separate comparison. We have 585 live serviced-office and coworking listings (Central 56, Wan Chai 33, Kwun Tong 32, Tsim Sha Tsui 31). These are priced per desk or per room per month and normally include management fees, utilities and basic facilities, so they should not be set directly against a rent per sq ft on gross floor area.
For Q4, staying in the core and relocating to upgrade both have their logic. In a market split by tier, the deciding factor is not which district is cheaper, but how specific the business requirement on location and specification actually is.
Basis of Figures
The market views in this article (the Q4 outlook for Central Grade A rents, and the assessment of take-up in other districts and Grade B space) are our own; they are not derived from site statistics. The transaction described was provided by our own agency team. All figures below are calculated from live listings on our platform, as at 30 September 2026:
- Sample: listings with status "displayed" — 2,149 offices, 613 industrial, 585 serviced offices
- District attribution: by the district recorded on the listing itself, the same basis used by the site's listing pages and district filters
- Median rent per sq ft: monthly rent divided by gross floor area for each listing, then the median for that district; listings missing rent or area are excluded, so the counted sample per district differs slightly from the total listing count
- Grade tiers: grouped by the grade recorded against the listing's building. AAA/AA/A are our own sub-tiers within the official "Grade A" band, not a government classification (the official system has only Grades A, B and C). "Unrated" means we have not assigned a grade to that building — it does not mean Grade B
- Cross-check: medians were recalculated using the rent-per-sq-ft field supplied with the listing source; the main districts agree (Central and Admiralty both HK$52, Causeway Bay HK$45, Tsim Sha Tsui HK$35, Kwun Tong HK$20)
- Sample threshold: the office-versus-industrial comparison lists only districts with at least 15 live listings on both sides. Districts with too small a sample produce medians that do not represent them — a district with only two or three office listings can show "offices cheaper than industrial", which is a sampling artefact
- No shop figures: 191 live shop listings, with several districts at samples of only 2 to 7
Live listings reflect landlords' asking prices, not completed transactions, and do not form a time series; changes in a live median should not be used to infer the rate at which rents are rising or falling. The transaction cited is an individual case and does not represent an average for the district.